
More from Milk. The Tuesday signals briefing: this week, the dairy and cheese markets and the pressure on the plants that buy the milk.
Two weeks ago we wrote that Cheddar was the product the market recovery had left behind. Powder and butter were climbing and cheese had barely moved. September changed that. Mild Cheddar put on £270 a tonne, more than any of the other products AHDB tracks, and the world market pushed it harder still. The catch is timing. Milk buyers had already announced higher October prices before Cheddar moved, and AHDB says even the new Cheddar price does not cover them.
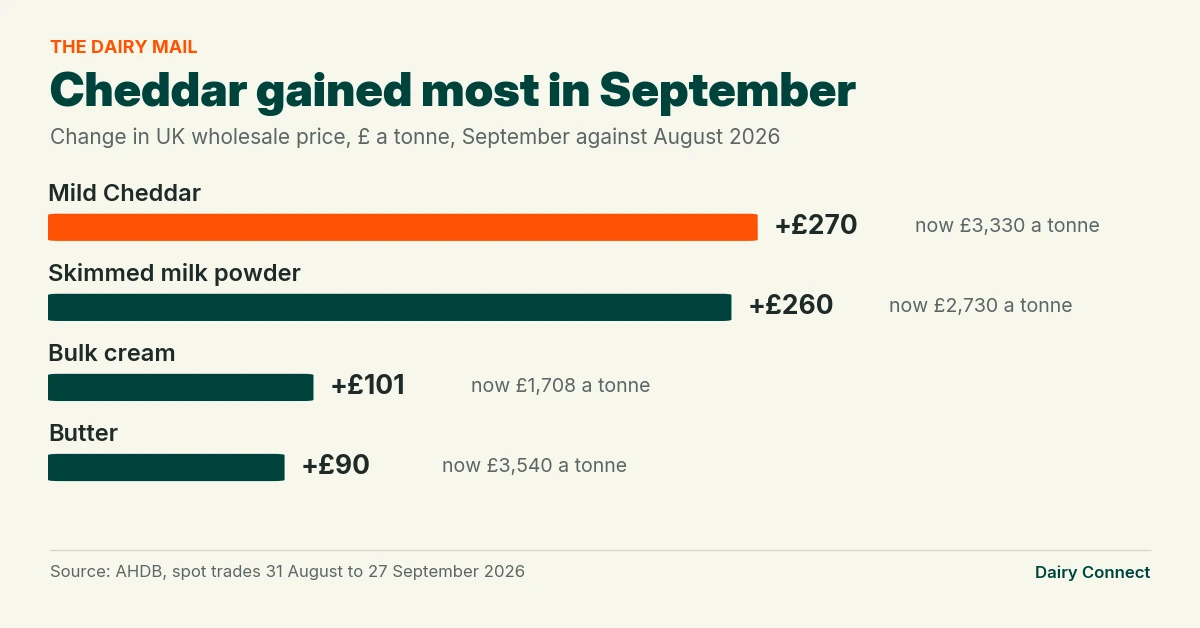
Cheddar has caught up
AHDB now has mild Cheddar at £3,330 a tonne, based on spot trades between 31 August and 27 September. In August it moved by £10. This time it rose by 9%. Skimmed milk powder rose faster in percentage terms, at 11%, but in cash Cheddar came out on top.
The Global Dairy Trade auction on 15 September told the same story, only louder. Cheddar was up 16.5% to US$4,075 a tonne, and Cheddar for October delivery was up 23.7%. Nothing else joined in. Butter fell by 5.7%, powder barely moved and the overall index slipped by 1.1%. It is worth remembering that at the auction on 1 September, October and November Cheddar fell by more than 12%, so one result is not a trend.
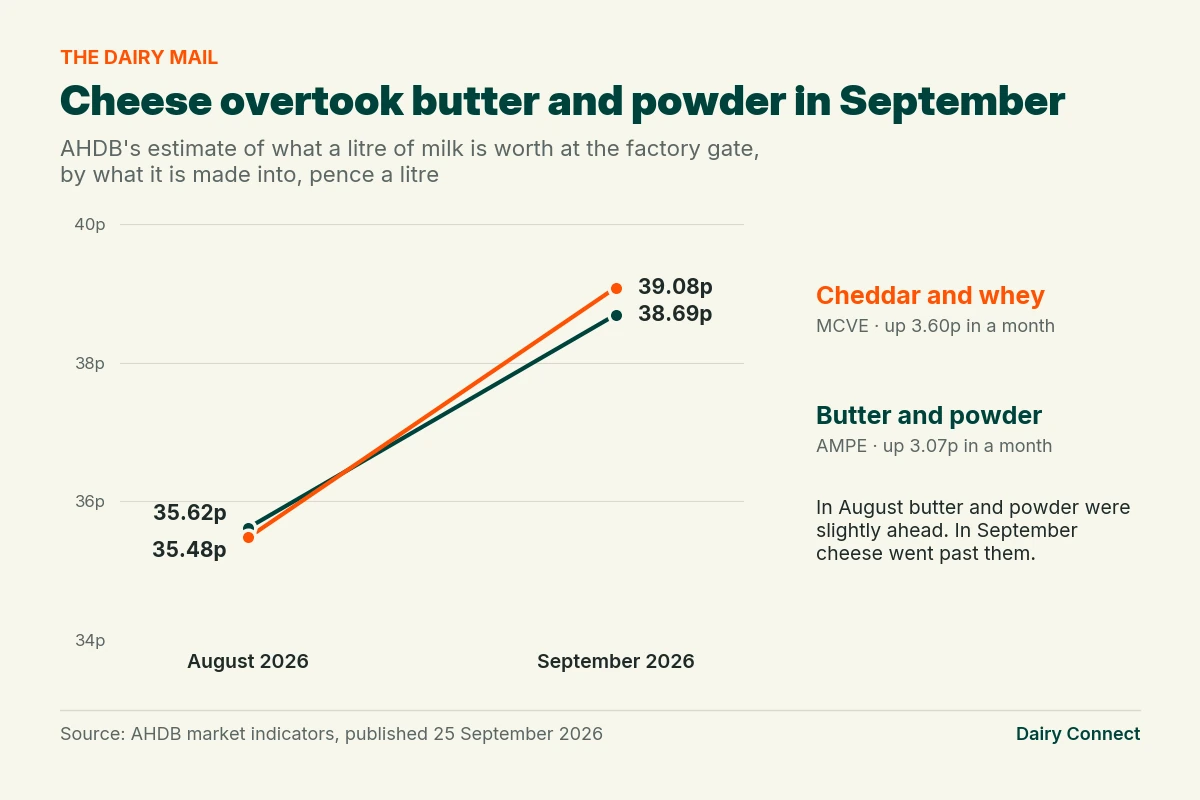
Cheese is now worth more than butter and powder
AHDB works out what a litre of milk is worth at the factory gate, depending on what it is made into. Made into Cheddar and whey, a litre was worth 39.08 pence in September, up 3.60 pence. Made into butter and powder, it was worth 38.69 pence. In August it was the other way round, with butter and powder slightly ahead.
So what does that mean for the milk cheque? AHDB's rule of thumb is that a 1 pence move in its overall Milk Market Value, now 39.00 pence, feeds through as about 0.5 pence on the average GB milk price, usually three months later. Its latest model has manufacturing milk up 1.8 pence a litre in December. AHDB is careful to add that strong global milk supplies and high stocks in store could hold prices back, and that not every contract will follow the model.
The milk bill got there first
This is where it gets awkward for cheese makers. The October milk price rises were announced in late August and early September, weeks before AHDB published September's Cheddar price on 25 September.
Müller pays 37 pence a litre from 1 October, up 2 pence, for suppliers meeting its Advantage conditions. Freshways goes to 38 pence, up 6 pence, including a 1 pence sustainability bonus. First Milk pays 39 pence including its member premium. Barbers, which makes cheese, adds 2.37 pence from 1 October. That takes it to 40.11 pence on the basis milkprices.com uses for its manufacturing league table, or 39 pence, up 2.30 pence, on Barbers' own standard litre, which assumes lower fat and protein.
It is tempting to set those prices against AHDB's September cheese figure of 39.08 pence, but the answer depends on which litre you pick. One Barbers price sits above it and the other sits just below. AHDB's figure is also a model built on standard costs and yields, and it leaves out the cost of collecting milk from farms. So we will leave that sum alone and let AHDB make the point in its own words. Cheddar prices, it says, "remain too low to cover milk price rises" for October.
Barbers sounds more relaxed. It says cheese stocks "remain tight" and that it is confident "the market fundamentals will deliver high cheese markets to support the milk pricing required". AHDB, talking about dairy stocks more broadly, thinks high stocks in store will limit rises. Both could be partly right, and October's wholesale figures should show which way it is going.
Less milk, and a packaging bill on the way
Plants are also handling less milk than a year ago. GB deliveries averaged 33.02 million litres a day in the week to 19 September, 3.4% down on the same week last year, or about 1.16 million litres a day. That is a national figure, so it will not match every site. A plant taking in that much less is spreading the same fixed costs over fewer litres.
Then there is packaging. PackUK expects to confirm year-two fees under extended producer responsibility in November, and to send out the first 2026 to 2027 notices of liability by the end of that month. It is one cost that does not shrink when milk volumes do.
What to keep an eye on
- November milk prices, due any day. None had been announced by Monday 28 September. A second rise from the cheese buyers would add to a bill that AHDB says Cheddar does not yet cover.
- Tuesday 6 October: the next full Global Dairy Trade auction.
- October: AHDB's October wholesale prices, which will show whether Cheddar holds on to September's gain.
- By the end of November: PackUK's confirmed packaging fees.
The numbers
UK wholesale prices, September 2026
| Product | £ a tonne | Change on August |
|---|---|---|
| Mild Cheddar | 3,330 | +£270 (+9%) |
| Skimmed milk powder | 2,730 | +£260 (+11%) |
| Bulk cream | 1,708 | +£101 (+6%) |
| Butter | 3,540 | +£90 (+3%) |
AHDB, spot trades agreed 31 August to 27 September 2026.
Global Dairy Trade auction, 15 September 2026
| Product | Change | Price |
|---|---|---|
| Cheddar | +16.5% | US$4,075 a tonne |
| Cheddar, October delivery | +23.7% | |
| Butter | −5.7% | |
| Skimmed milk powder | +0.1% | |
| Overall index | −1.1% |
What a litre of milk is worth at the factory gate, AHDB
| Measure | What it values | September 2026 | August 2026 |
|---|---|---|---|
| MCVE | A litre made into mild Cheddar and whey | 39.08p | 35.48p |
| AMPE | A litre made into butter and skimmed milk powder | 38.69p | 35.62p |
| Milk Market Value | All routes, weighted by how UK milk is used | 39.00p | 35.51p |
Farmgate milk prices
| Processor | Price a litre | Change | From |
|---|---|---|---|
| Barbers (cheese maker) | 40.11p on milkprices.com league table basis; 39p on Barbers standard litre | +2.37p; +2.30p | 1 October |
| First Milk | 39p, including member premium | October | |
| Freshways | 38p, including 1p sustainability bonus | +6p | October |
| Müller (Advantage suppliers) | 37p | +2p | 1 October |
GB milk deliveries: 33.02 million litres a day in the week to 19 September 2026, 3.4% below the same week last year (AHDB).
Source table
| Figure in copy | Value | Source | Period | Published |
|---|---|---|---|---|
| Mild Cheddar, SMP, bulk cream, butter, UK wholesale | £3,330 (+£270, +9%), £2,730 (+£260, +11%), £1,708 (+£101, +6%), £3,540 (+£90, +3%); percentages as rounded by AHDB | AHDB UK wholesale prices | Spot trades 31 Aug to 27 Sept 2026 | 25 Sept 2026 |
| Mild Cheddar, August movement (baseline only) | +£10 to £3,060 | AHDB UK wholesale prices | August 2026 | 9 Sept 2026 |
| Cheddar "remain too low to cover milk price rises" for October | quote | AHDB UK wholesale prices commentary | September 2026 | 25 Sept 2026 |
| GDT event 412 | index −1.1%; Cheddar +16.5% to US$4,075/t; Oct Cheddar +23.7%; butter −5.7%; SMP +0.1% | GDT event commentary; Cheese Reporter | 15 Sept 2026 | 15 to 16 Sept 2026 |
| GDT event 411, Oct/Nov Cheddar | down more than 12% | Cheese Reporter | 1 Sept 2026 | 2 Sept 2026 |
| AMPE, MCVE, Milk Market Value | 38.69ppl (+9%), 39.08ppl (+3.60ppl, +10%), 39.00ppl (+3.50ppl) | AHDB market indicators | September 2026 | 25 Sept 2026 |
| AMPE, MCVE, August (baseline only) | 35.62ppl, 35.48ppl | AHDB market indicators | August 2026 | 25 Aug 2026 |
| MMV to milk price relationship; December projection; stocks limiting upside | 1ppl MMV to c. 0.5ppl GB price, about three months later; manufacturing +1.8ppl December; "high stocks of product in stores" | AHDB projected farmgate milk prices | December 2026 projection | 25 Sept 2026 |
| GB milk deliveries | 33.02m litres/day, −3.4% y/y, −1.16m litres/day | AHDB UK daily milk deliveries | w/e 19 Sept 2026 | week of 21 Sept 2026 |
| Müller | 37ppl from 1 Oct, +2ppl, Advantage suppliers | Farmers Weekly, Farmers Guide | October 2026 | 1 to 2 Sept 2026 |
| Freshways | 38ppl from October, +6ppl, incl. 1ppl sustainability bonus | Farmers Weekly, Farmers Guide | October 2026 | 1 to 2 Sept 2026 |
| First Milk | 39ppl from October incl. member premium | FarmingUK, Farmers Weekly | October 2026 | 2 Sept 2026 |
| Barbers | 40.11ppl (+2.37ppl) at milkprices.com manufacturing league table criteria; 39ppl (+2.30ppl) at Barbers Standard Litre | Barbers announcement, "2.37ppl milk price increase for Barbers from 1st October" | From 1 October 2026 | 1 Sept 2026 |
| Barbers, cheese stocks quote | "remain tight"; "the market fundamentals will deliver high cheese markets to support the milk pricing required" | Farmers Weekly | n/a | c. 1 Sept 2026 |
| EPR year-two timing | confirmed fees calculated in November; initial 2026 to 2027 notice of liability by end of November | FDF EPR overview | 2026 to 2027 | Sept 2026 update |
| GDT event 413 | Tuesday 6 October, 12:00 UTC | GDT events calendar | n/a | n/a |
About the figures in this briefing
Where a number has a limit, this is where we say so.
Barbers' price. Barbers quotes two figures for October: 40.11ppl on milkprices.com manufacturing league table criteria, and 39ppl on its own lower-constituent standard litre. We have not compared either with AHDB's MCVE of 39.08ppl, because the result depends on which litre is used, and MCVE is a modelled indicator using standard costs and yields that excludes milk collection. An earlier draft dated the 40.11ppl to September and compared it with MCVE; both were wrong and have been removed.
Wholesale prices. AHDB's wholesale figures are assessments of spot trades, not the prices any processor achieved across its full sales book. Much cheese is sold on contract.
The December projection. This is AHDB's model, published 25 September. AHDB notes that processors' markets and contract terms can produce different results.
Global Dairy Trade. Single auctions move sharply in both directions. Cheddar fell by 6.6% on 1 September and rose by 16.5% on 15 September. A GDT Pulse auction runs at 12:00 UTC today, after this briefing publishes. The next full event is 6 October.
Stocks. Barbers says cheese stocks "remain tight". AHDB's September projection refers to high stocks of product in store. We have reported both and attributed each. We have not said which is right.
Milk deliveries. The weekly figure is a seven-day rolling average from AHDB's daily series and will revise. National intake does not show what any single plant received.
Removed after verification. The Dairygold paragraph (July announcement, outside the four-week window, with no newer primary-source update found). The August monthly deliveries comparison and AHDB's August description of stocks, both superseded by September evidence.
Sources & data
- AHDB: UK wholesale prices, spot trades agreed 31 August to 27 September 2026, published 25 September 2026
- AHDB: UK wholesale prices, August 2026, published 9 September 2026
- AHDB: market indicators, AMPE, MCVE and Milk Market Value, September 2026, published 25 September 2026
- AHDB: projected farmgate milk prices, December 2026 projection, published 25 September 2026
- AHDB: UK daily milk deliveries, week ending 19 September 2026
- Global Dairy Trade event 412, 15 September 2026, and event commentary, as reported by Cheese Reporter
- Global Dairy Trade event 411, 1 September 2026, as reported by Cheese Reporter
- Global Dairy Trade: GDT Events calendar, accessed 28 September 2026
- Müller, First Milk and Freshways October 2026 milk price announcements, as reported by Farmers Weekly, Farmers Guide and FarmingUK, 1 and 2 September 2026
- Barbers: October 2026 milk price announcement, 1 September 2026, and Farmers Weekly, c. 1 September 2026
- Food and Drink Federation: extended producer responsibility overview, September 2026 update
Published by The Dairy Mail, Dairy Connect: https://www.dairy-connect.com/the-dairy-mail/markets-and-manufacturing-briefing-29-september/
